Elevation Certificate Questions After Heavy Lake-Effect Rain
Lake-effect rain does not mess around near Cleveland. It can dump inches of water in a single day, and that water goes somewhere. Once it shows up in a yard or near a foundation, owners start asking real questions about their elevation certificate. Here is what that document can and cannot tell you after a heavy storm.
Heavy Rain Can Raise New Questions About a Property’s Elevation
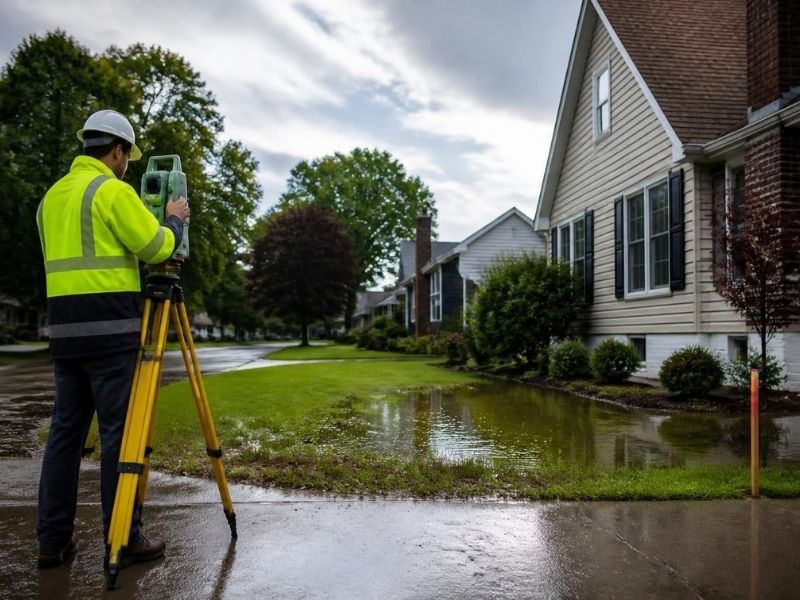
Days of lake-effect rain can expose problems fast. Water pools in low spots. Yards that normally drain fine suddenly hold puddles for hours. Owners look at all this and start to wonder if their property sits lower than they thought.
Some owners even start to question whether their home was ever properly assessed for flood risk in the first place. A few inches of standing water near a foundation can feel alarming, especially the first time it happens. That reaction makes sense. Nobody wants water creeping toward their home.
Seeing water after a storm is real. But it does not automatically tell you anything about a property’s official flood zone status. A yard can flood during a heavy rain event and still sit outside any mapped flood hazard area. Drainage and flood zone status are two separate things, and mixing them up leads to the wrong conclusions.
This is where an elevation certificate helps. It gives you measured, documented numbers. These numbers show how the structure’s elevation compares to flood-related reference levels used by FEMA and local floodplain offices. That is a much better starting point than judging things by how deep the water looked in the driveway.
Building Elevations Matter More Than the Depth of Water Seen in the Yard
A lot of homeowners focus on the wrong number after a storm. They remember how many inches of water sat in the yard. That number matters less than most people think. What actually matters is the elevation of the structure itself, not the temporary puddle sitting next to it.
An elevation certificate records a few key measurements. The lowest floor elevation shows the height of the lowest livable floor in the building. Adjacent grade elevations show the height of the ground touching the structure, both at its lowest and highest points. Some certificates also record the elevation of outdoor equipment, like an HVAC unit or a generator.
Each of these numbers plays a specific role. The lowest floor elevation matters most for flood insurance purposes. Adjacent grade elevations help explain how water moves around the foundation itself. Equipment elevations matter because a flooded HVAC unit or electrical panel can cause expensive damage even if the main living space stays dry.
These professional measurements give a far more useful picture than any guess based on storm damage. A puddle in the yard tells you almost nothing about how the actual building relates to flood risk. The certificate does, because it comes from precise surveying instruments instead of a glance out the window during a storm.
Changes Around the Property Can Affect Older Elevation Information
An elevation certificate is only accurate for the moment it was measured. Once things change on the property, that old data can stop matching reality. This catches a lot of owners off guard, especially if they bought the home years after the certificate was issued.
New grading can shift the ground level around a foundation. A new driveway can change how water moves across the site. An addition can create a new lowest floor elevation that the original certificate never accounted for. Landscaping projects, retaining walls, and drainage work can all quietly change the conditions around a home too.
Even small projects add up over time. A homeowner might regrade a section of yard for a garden. A neighbor might install a French drain that changes how water flows onto the adjoining property. None of these projects seem significant on their own, but together they can shift the accuracy of an old certificate more than people expect.
If any of these changes happened since the last certificate was issued, that document may no longer reflect current conditions. This matters even more after a season of heavy lake-effect storms, when many owners start noticing drainage issues for the first time. Getting updated measurements from a licensed surveyor is worth considering if the property has changed in any of these ways.
Flood Maps and Elevation Certificates Provide Different Pieces of Information
People often treat a FEMA flood map and an elevation certificate as if they answer the same question. They do not, and confusing the two after a storm leads to bad assumptions.
A FEMA flood map identifies mapped flood hazard areas across a broad region. It is built for wide coverage, not individual property detail. An elevation certificate does something more specific. It records the exact measured elevations at one property, done by a licensed surveyor standing on that exact lot.
Experiencing water buildup during a storm does not mean the FEMA map is wrong. Stormwater accumulation can happen for plenty of reasons that have nothing to do with mapped flood risk, including poor site grading, clogged storm drains, or local drainage systems that simply get overwhelmed during an unusually heavy rain event.
Looking at both the map and the certificate together gives owners a much clearer picture than relying on either one alone. The map shows the broad risk category. The certificate shows the specific numbers for one property. Both pieces matter, and neither one replaces the other.
Accurate Elevation Information Helps Guide the Next Property Decision
After a rough storm season, property owners often end up talking to several different people. Floodplain officials might get involved if there are recurring issues. Engineers may need to review drainage. Lenders and insurers sometimes ask questions too, especially during a refinance or a policy renewal.
Having current elevation data on hand makes every one of these conversations go smoother. Instead of guessing based on how bad the last storm looked, everyone can work from the same documented numbers. That consistency matters when real decisions are on the table, whether the conversation is about insurance premiums or a drainage repair plan.
This data is also useful before any future work on the property. Drainage improvements, renovations, and mechanical equipment relocation all benefit from knowing the property’s real elevations first. Planning a project around guesswork tends to create more problems than it solves.
An elevation certificate will not stop the next lake-effect storm from happening. What it does is give owners solid, documented information to decide what additional review, if any, makes sense next. That documentation turns a stressful, confusing situation into one with real answers behind it.
